September gave buyers more room to shop, but not a broad discount on every house. Fewer homes sold, the metro median slipped a little, and mortgage rates made the monthly payment harder to swallow.
The difference between a detached house and a condo matters more than the headline.
Fewer sales, prices close to last year
Across the 11-county Denver metro, 3,310 homes sold in September, down 17% from last year. The median sale price was $583,948, down 1.3%. Sales also fell about 8% from August, and the median eased about 2%.
Homes that sold took a median 32 days, compared with 35 last September. That’s a little faster than last fall, but slower than August’s 27 days. This is not a market where everything is flying off the shelf.
There are about 15,800 homes for sale now and another 4,600 under contract. At September’s sales pace, that’s nearly five months of supply. Buyers have choices. Sellers have competition.
The house and the condo are not having the same fall
The combined median hides three different stories:
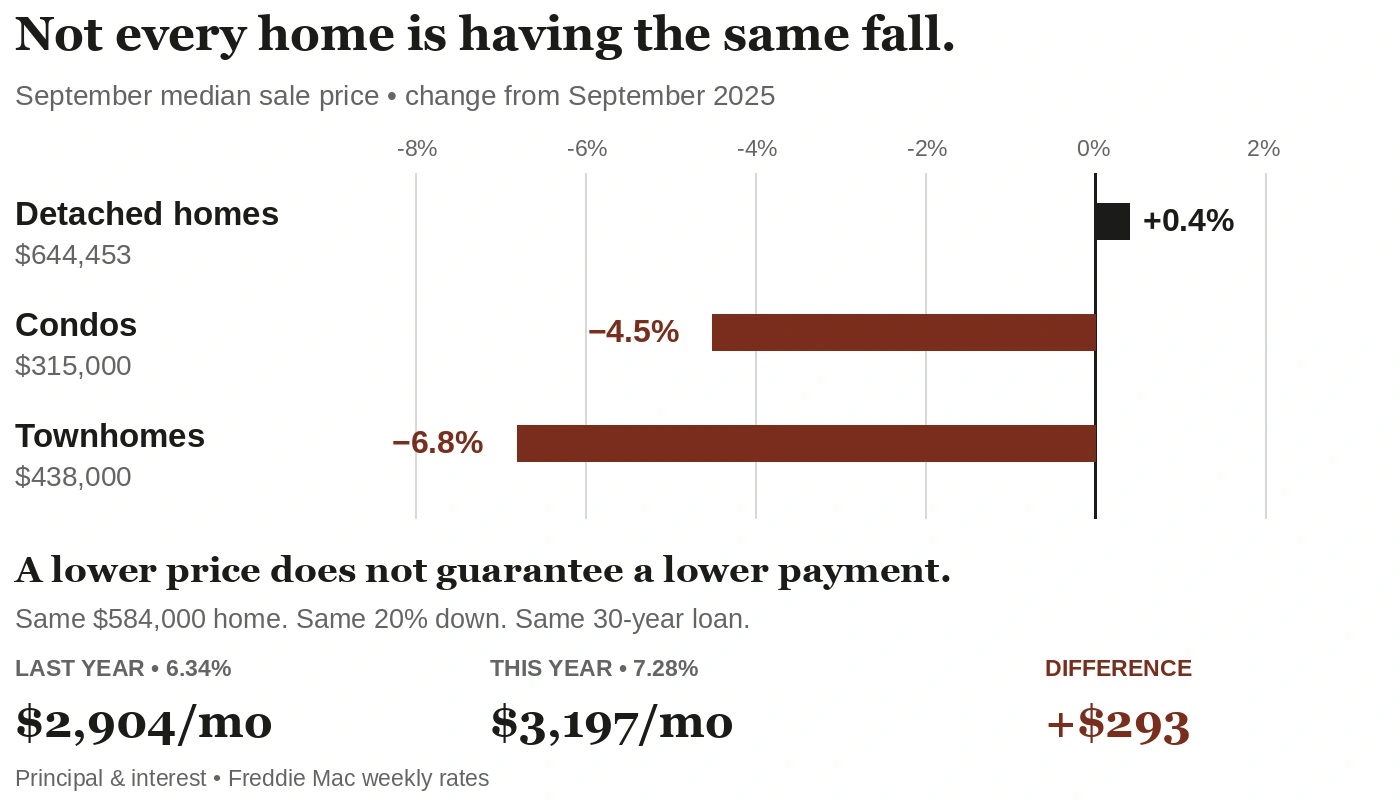
- Detached houses: $644,453 median sale price, +0.4% from last year; 28 median days on market.
- Condos: $315,000 median sale price, −4.5% from last year; 52 median days on market.
- Townhomes: $438,000 median sale price, −6.8% from last year; 38 median days on market.
Detached prices were essentially flat, and those homes sold five days faster than last year. Condos took six days longer and sold at a lower median. Townhome prices were lower too, with little change in selling time.
That doesn’t tell you what a particular home is worth. It tells you why “the Denver market” is too broad an answer when you’re deciding what to offer or where to list. A condo seller and a detached-home seller may need very different plans.
More than half of September’s sales closed below asking price. Negotiating is normal. But a below-list sale isn’t automatically a bargain, any more than an ambitious asking price is proof of value. Compare the actual alternatives.
Rates are doing more damage to the payment
Freddie Mac’s weekly 30-year average rose to 7.28%, from 7.03% the week before and 6.34% a year ago. Mortgage News Daily’s daily index ended Friday at 7.57%.
On a $584,000 home with 20% down, the monthly principal-and-interest payment is about $3,197 at 7.28%. At last year’s 6.34%, the same loan would have cost about $2,904. Roughly $290 more each month, without buying any more house.
A small drop in price doesn’t necessarily mean a smaller payment. Run the numbers on the home you’re considering, including taxes, insurance and any HOA dues, before deciding what “affordable” looks like.
What I’d do with this
Buying: Use the extra selection. Compare homes, ask about the ones that have been sitting, and negotiate around the total cost—not just a few thousand dollars off the price. Ask your lender to compare a price reduction with money toward closing costs or a rate buydown. Which one helps depends on your cash, loan and how long you expect to keep it.
Selling: Start with your actual competition. If you own a condo, don’t borrow confidence from detached-house numbers. Look at what similar units are selling for, what buyers can choose instead, and what the payment looks like. Price and presentation need to make sense together.
If you own too much real estate, or not enough, call me, I can fix that for you!